When cash runs short, CA advisory services help a UAE business choose between talking to lenders, refinancing and a formal court process. The best CA advisory services start with numbers that creditors can trust, not with a legal filing. Many owners wait until a cheque bounces or a bank freezes a facility. By then, the options are narrower and the terms are harder. This guide explains each route, how the 2023 bankruptcy law works, and where our transaction advisory team fits. It also covers the corporate tax rules that change the maths of any deal.
Key Takeaways
- Informal renegotiation is fastest and cheapest, but it only works when lenders believe your forecast.
- Federal Decree-Law No. 51 of 2023 offers preventive settlement, court supervised restructuring and bankruptcy for mainland businesses.
- CA advisory services build the 13 week cash flow, lender pack and viability model that every route needs.
- Corporate tax caps net interest deductions and can treat a debt write off as a gain, so model tax before you sign.
What Are Your Options When Cash Flow Tightens?
Most UAE businesses under strain have three informal options before any court is involved: renegotiate terms with lenders, reschedule repayments, or refinance with new money. Each needs a credible forecast and early contact. The route you choose depends on how deep the shortfall is and how many creditors you must bring along.
Renegotiation is the lightest touch. You ask a bank or key supplier for a short payment holiday, lower instalments or a covenant waiver. Banks respond better when you call before a missed payment, not after. Bring a clear explanation of the cause and a plan for recovery. A lender who sees a realistic forecast is far more likely to agree a temporary change than one who sees only a request for more time.
Rescheduling stretches the repayment period so monthly outflows fall. Refinancing replaces expensive or short term debt with longer facilities, sometimes from a new lender. A shareholder may also inject funds or convert a loan into equity. Each option has a cost in fees, security or dilution, so compare them on one page. CA advisory services can set out that comparison so the board sees the trade offs in one view.
These informal routes fail when there are too many creditors to agree, or when one lender moves to enforce. That is the point where a formal process under the bankruptcy law becomes worth considering.
How Does the UAE Bankruptcy Law Support Debt Restructuring?
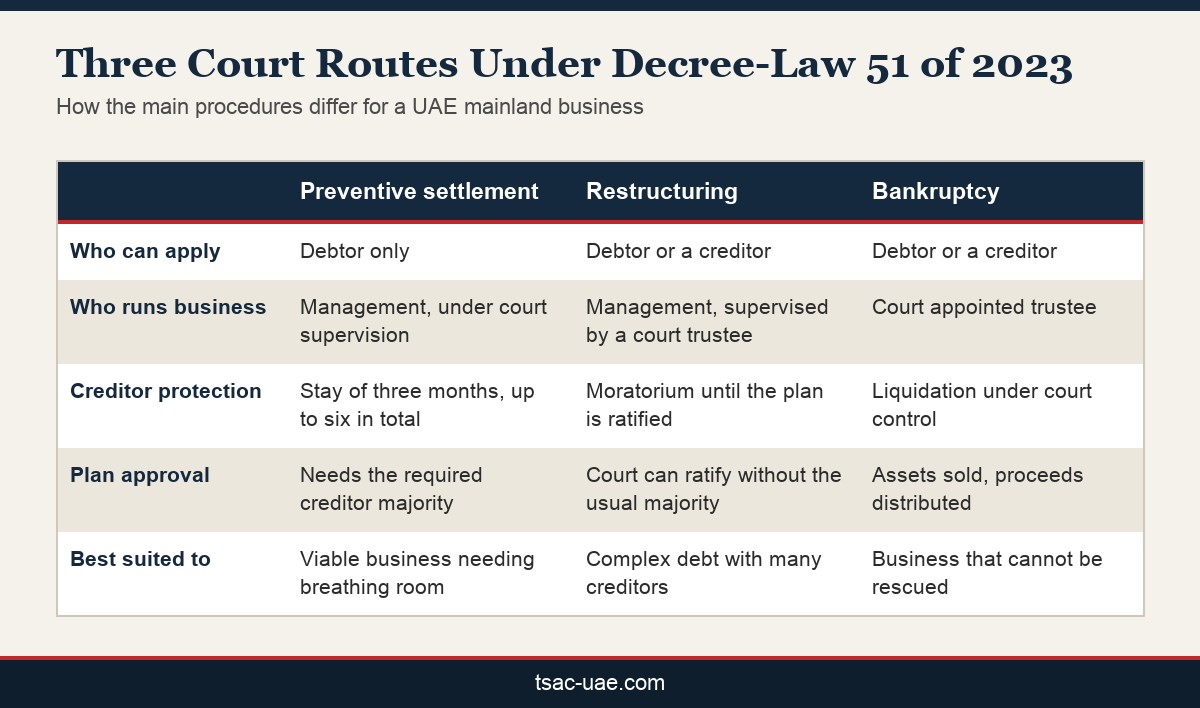
Federal Decree-Law No. 51 of 2023 on Financial Restructuring and Bankruptcy came into force on 1 May 2024 and replaced the 2016 law. It gives distressed mainland businesses three court routes: preventive settlement, restructuring and bankruptcy. A dedicated Bankruptcy Court supervises each one, and Cabinet Resolution No. 94 of 2024 sets the executive rules.
Preventive settlement is the lighter route. Only the debtor can apply, and management stays in control under court supervision. An automatic stay protects the business for three months, which the court can extend up to six months in total. It suits a business that is still viable but needs breathing room to agree a plan.
Restructuring is for more complex cases. The debtor or a creditor can open it, and a court appointed trustee supervises management. A moratorium runs until the court ratifies the plan, which is normally due within six months. The court can ratify a plan even without the usual creditor majority.
Bankruptcy is the last resort, where a trustee takes over and the assets are sold. The law does not apply in ADGM or DIFC, which run their own regimes. Free zones with their own insolvency rules may also differ, so check your licence authority first. Executive rules can also change, so confirm the current procedure with legal counsel before you file anything.
What Do CA Advisory Services Deliver in a Restructuring?
Whether the route is informal or court supervised, lenders and judges want the same evidence: a realistic short term cash forecast, an honest view of the business, and a plan that shows creditors recover more than in liquidation. CA advisory services prepare that evidence and keep it updated as negotiations move forward week by week.
The core tool is a 13 week cash flow forecast. It tracks receipts and payments week by week, flags the low point, and shows how much headroom each option creates. Good cash flow forecasting in the UAE also covers VAT payments, salary dates under WPS and rent cheques, which often cluster. The forecast is refreshed every week, and actual results are compared against it so lenders can see that management is in control.
The second tool is a lender pack. It explains what went wrong, what has already changed, and what you are asking for. It draws on clean monthly management accounts, because lenders lose confidence fast when numbers shift between versions.
The third tool is a viability model. It tests whether the business can service its restructured debt over three to five years under base and downside cases. Where a sale of assets or a new investor is part of the plan, an independent valuation supports the price that creditors are asked to accept.
How Does Corporate Tax Treat Interest and Debt Write Offs?
Restructuring changes your tax position as well as your cash. Under UAE corporate tax, net interest deductions are capped once they exceed AED 12 million, and a lender writing off part of your debt can create an accounting gain. Both effects should sit inside the viability model before any term sheet is signed.
The general interest limitation rule in Article 30 of the Corporate Tax Law and Ministerial Decision No. 126 of 2023 allows net interest expenditure up to the higher of AED 12 million or 30% of adjusted EBITDA. Any disallowed amount can be carried forward for up to ten tax periods. Our deep dive on interest limits walks through the calculation.
Debt forgiveness needs separate care. Ministerial Decision No. 134 of 2023 treats the forgiveness of a liability as a realisation event, recognised under your accounting standards. Because taxable income starts from accounting profit, a write off can raise taxable income in the year it happens. Available tax losses can usually offset up to 75% of taxable income.
Related party loans, group transfers and qualifying group relief add further layers. Read the FTA corporate tax guidance and have corporate tax support review the deal before it is final.
When Should a UAE Business Bring in an Adviser?
The right time is earlier than most owners think. Warning signs include stretched supplier terms, frequent overdraft use, breached covenants and VAT or salary payments funded by new borrowing. Bringing in advisers at the first sign gives you more options, more credibility with lenders and more time to protect value for shareholders.
Start with a quick diagnostic. An adviser reviews the latest accounts, ageing reports and facility letters, then builds a first cash forecast within days. That shows whether you face a short timing gap or a deeper structural problem. A timing gap may need only a short facility, while a structural problem needs a full plan.
Choose an adviser who can cover accounting, tax and lender negotiation together. Restructuring decisions affect all three, and splitting them between firms slows everything down. Ask how they will report progress and who will speak to the banks.
Finally, keep legal counsel close if a court process is likely. Advisers prepare the numbers, while lawyers handle filings and creditor claims. The Ministry of Finance corporate tax overview is a useful reference for owners preparing that conversation.
Conclusion
Cash flow strain does not have to end in liquidation. Early contact with lenders, a credible forecast and the right legal route can keep a viable business trading. CA advisory services give you the 13 week forecast, the lender pack and the tax model that each route depends on. TSAC works with UAE SMEs from offices in Dubai and Sharjah on accounting, tax and transaction support. If your business is under pressure, book a free consultation and we will review your position and options with you.
Frequently Asked Questions
What are CA advisory services in a debt restructuring?
They are the financial work behind a restructuring. Advisers build the 13 week cash flow forecast, the lender pack and the viability model, and they check the corporate tax effect of new terms before the business signs anything.
What is preventive settlement under the UAE bankruptcy law?
It is the lighter court route under Federal Decree-Law No. 51 of 2023. Only the debtor can apply, and management stays in control under court supervision, with a stay of three months extendable to six months in total.
Can a creditor start a restructuring against my company?
Yes, under the 2023 law a debtor or a creditor can open restructuring proceedings. A court appointed trustee then supervises management, and a moratorium applies until the court ratifies the plan. Preventive settlement, by contrast, can only be started by the debtor.
Does the bankruptcy law apply to free zone companies?
It does not apply in ADGM or DIFC, which run their own insolvency regimes. Other free zones may have their own rules too. Check your licensing authority and take legal advice before assuming the federal procedures are available to you.
How much interest can my business deduct for corporate tax?
Net interest expenditure is deductible up to the higher of AED 12 million or 30% of adjusted EBITDA. Any disallowed amount can be carried forward for up to ten tax periods. Banks and insurers follow different rules.
Is a debt write off taxable under UAE corporate tax?
It can be, because forgiveness of a liability is a realisation event, and the gain usually flows into accounting profit, the starting point for taxable income. Available tax losses may offset part of it. Model the effect before agreeing terms.
Should shareholders lend money to a struggling company?
Shareholder funding can bridge a short gap, but it needs proper documentation and arm’s length terms. Read our guide to shareholder loans for the transfer pricing and interest points to consider before any money moves between you and the company.
How do I know the tax impact of a restructuring plan?
Run the numbers before you sign. A tax impact review tests interest limits, write off gains, loss relief and group rules against your proposed terms. It shows the real cash cost of each option, not just the headline saving.